

Our newsletter covers news, industry perspectives, and updates from the USBC ecosystem. Check out our last report here.
This week:
USBC’s big unveiling at Money2020 Las Vegas
Simon McLoughlin: 2026 will be the year of tokenized deposits
A big shift for stablecoins in 2026
The future of digital identity won’t be self sovereign—for now
Stuff happens
1. USBC’s big unveiling at Money2020 Las Vegas
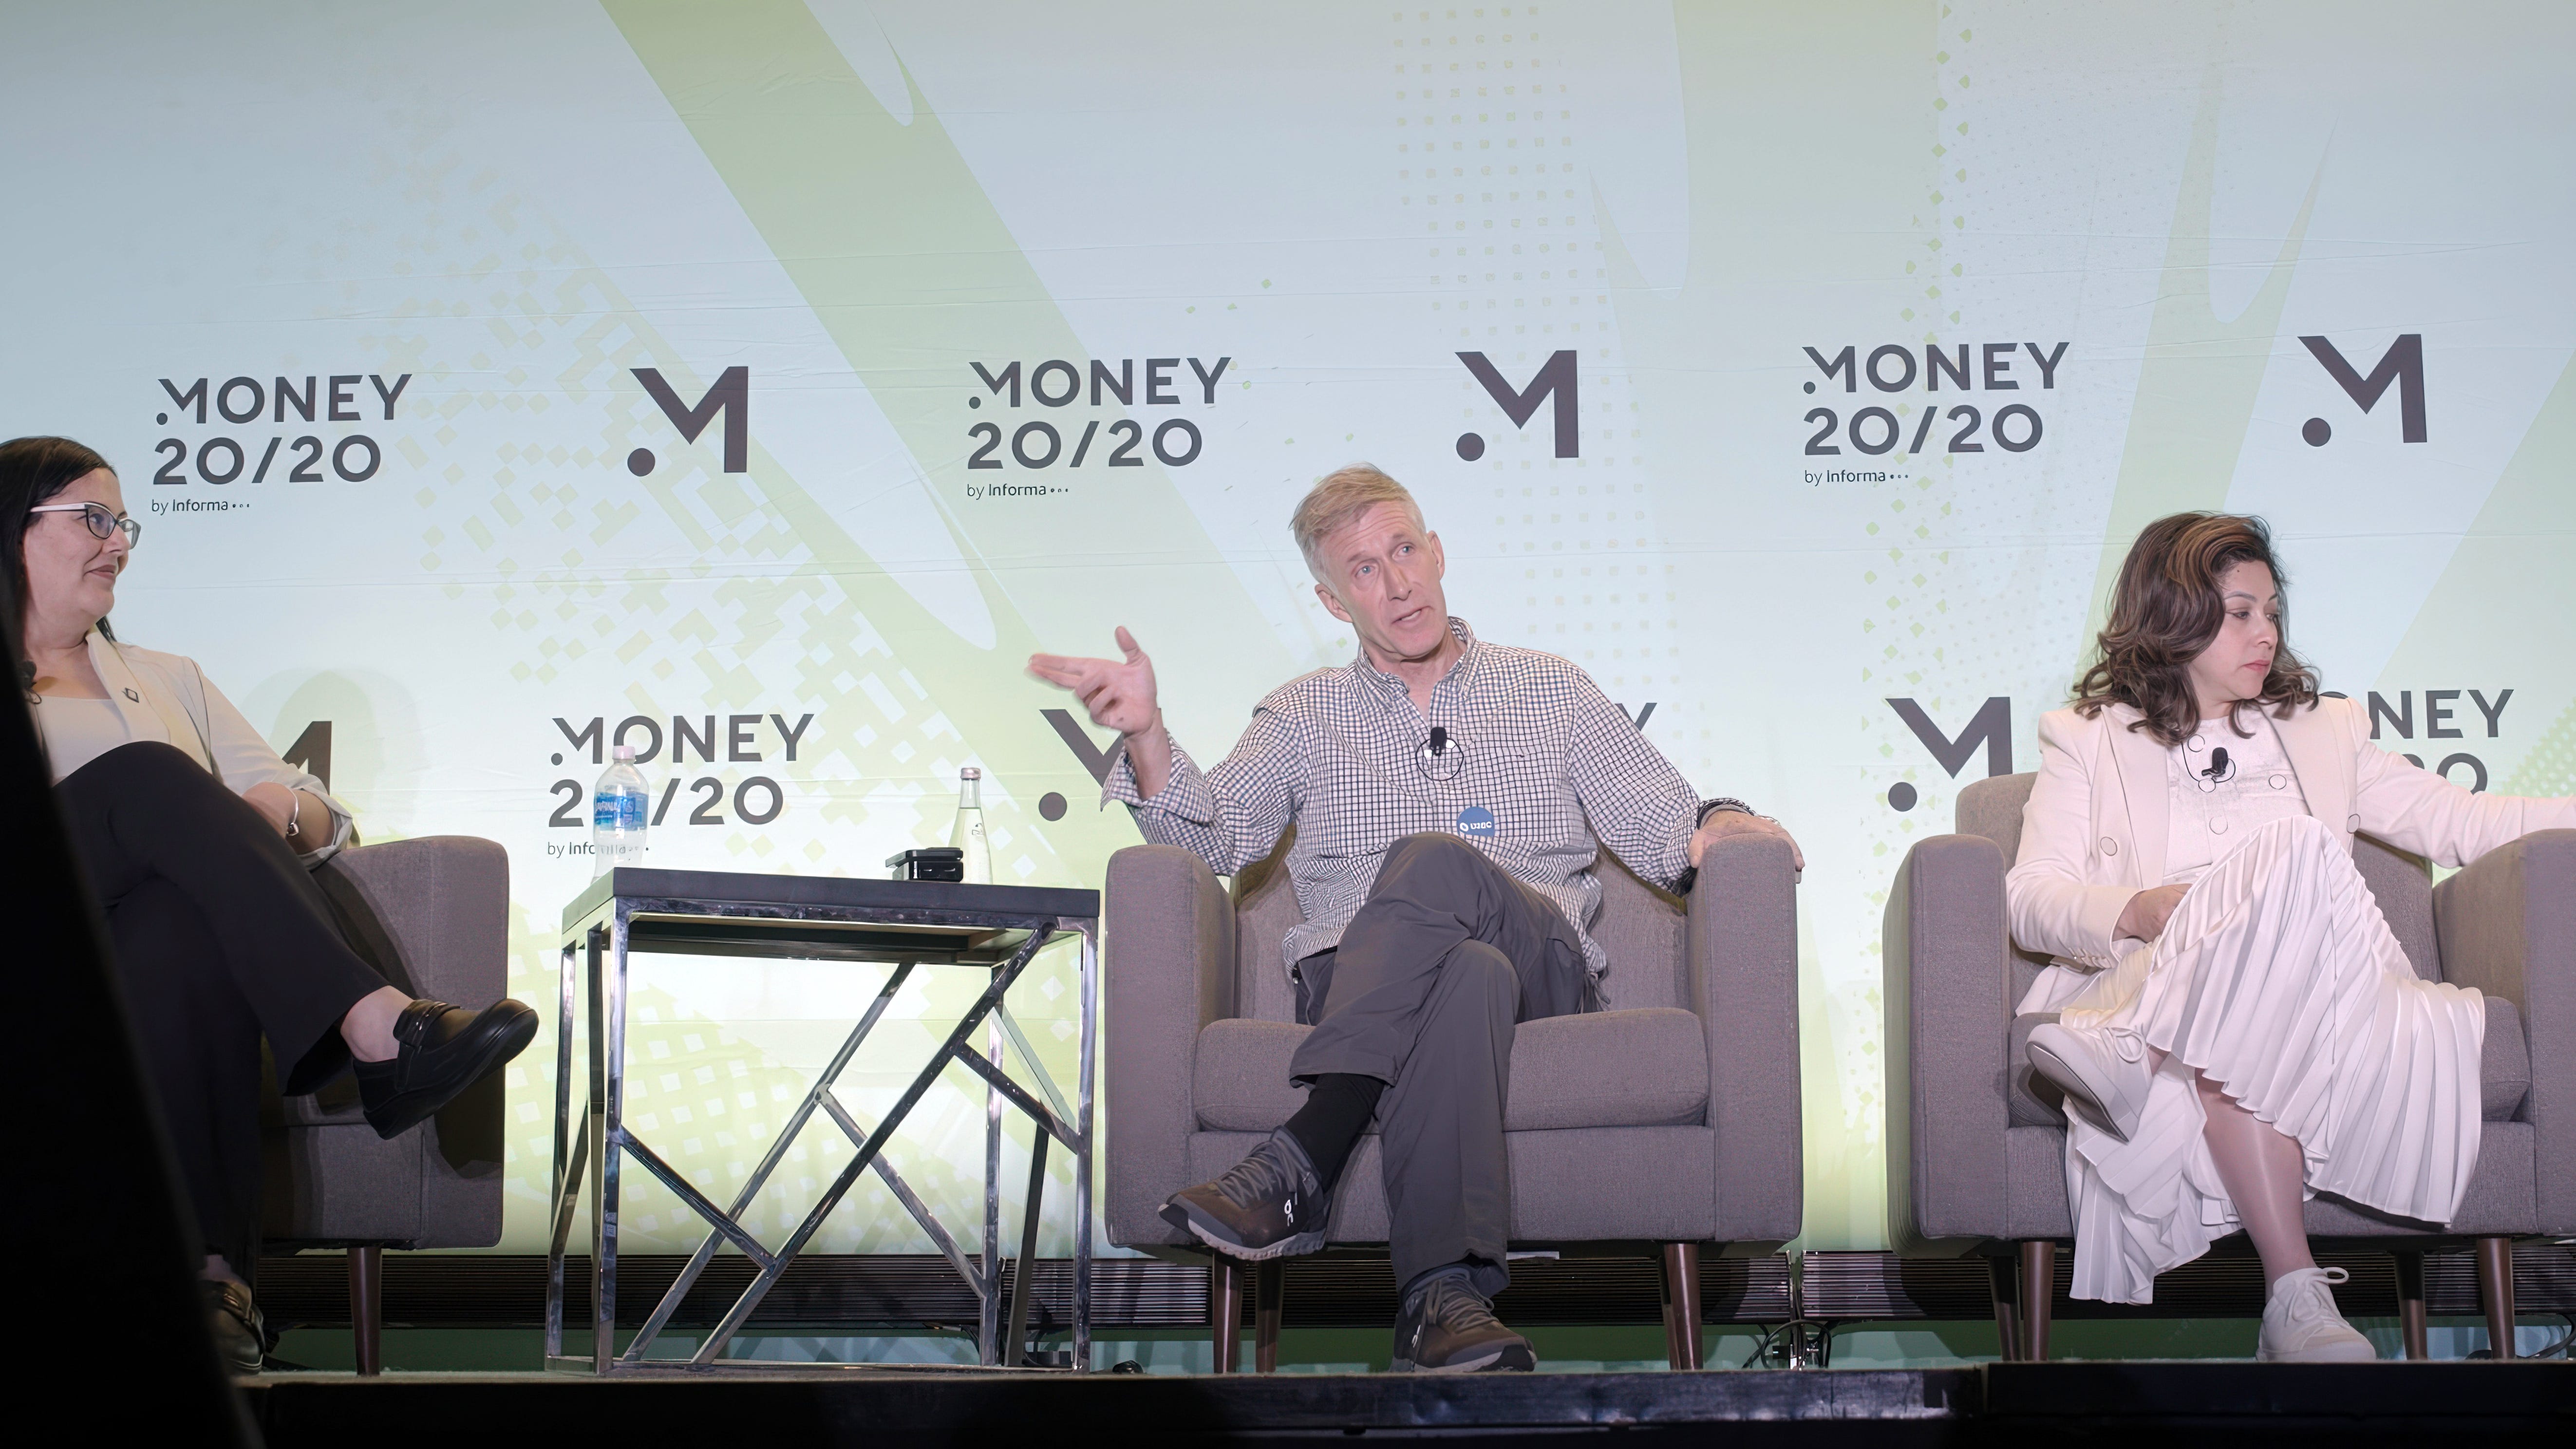
Back in October, the USBC team headed to Las Vegas for the year’s most influential U.S. fintech conference, Money2020, where we unveiled not only our vision for tokenized deposits but also our new partnership with Vast Bank and Uphold.
The big takeaway? The energy and interest around real U.S. dollars on chain is massive. If stablecoins showed the way, it could very well be tokenized deposits—backed by the consumer safeguards and compliance of the traditional banking system—that brings digital dollars to the masses.
2. Simon McLoughlin: 2026 will be the year of tokenized deposits
Uphold CEO Simon McLoughlin participated in CoinTelegraph’s predictions for 2026—it’s going to be a big year for tokenized deposits:
Stablecoins could have a strong competitor emerging: tokenized deposits.
Simon McLoughlin, CEO of Uphold, highlighted to Cointelegraph that tokenized deposits could disrupt stablecoin dominance by offering digital representations of traditional bank deposits directly on blockchains, while maintaining regulatory protections like deposit insurance.
As banks innovate with permissioned ledgers and programmable money features, tokenized deposits could become the preferred form of digital money for use cases requiring the security and stability of regulated banking, potentially challenging stablecoins’ current market lead. As McLoughlin said:
“If 2025 was the year of the stablecoin, 2026 will be the year of the tokenized deposit.”
3. A big shift for stablecoins in 2026
Digital dollars had a huge year in 2025 with stablecoins leading the way, fueled by further regulatory clarity in the U.S., but we’ll only see the space continue to mature in 2026.
One way we’ll see that play out is how the industry will deal with permissionless, identityless stablecoins from a risk and compliance perspective.
For Lead Bank, a major player in facilitating stablecoin payments, that means tightening risk controls and even de-risking, according to The Information’s Yuegi Yan, citing Michael Roddan’s recent report. (via Greg Kidd):
Most of the popular stablecoin payment startups, such as Stripe’s Bridge and BVNK, use Lead Bank to open accounts for users and process transactions. Its dominance is raising concerns that it could pose concentration risk for the stablecoin industry.
…
Our reporting shows the bank has been tightening its risk controls recently, adding restrictions to countries and sectors it would serve. Lead Bank CEO Jackie Reses said the bank is always active in how it deals with risks, and its efforts continuously evolve based on where it sees risks from clients’ offerings.
4. The future of digital identity won’t be self sovereign—for now
Preserving user privacy and agency remains a core tenet of the USBC ecosystem, but when we read Trinsic co-founder and CEO Riley Hughes’ excellent writeup on why self-sovereign identity and verifiable credentials haven’t made a market impact and why his company is now pivoting, we couldn’t help nodding our heads along the way.
His thinking isn’t far off from how we are thinking about the problem of digital identity. Ultimately, we need to empower and protect users while also delivering them the experience and convenience they deserve rather than compromising either for the sake of rigid ideals.
Here’s Riley:
I’ve not changed my convictions on the future I want to live in. Nor has my resolve wavered in my desire to build that future. But the market has spoken. Prematurely standardizing a pre-product/market fit technology won’t work — no matter how badly zealous advocates of SSI want it to. That is why Trinsic is no longer a general-purpose verifiable credential infrastructure company.
While I don’t expect a universal standard for digital IDs will happen anytime soon, new digital IDs continue to roll out every day. These digital IDs are sometimes built with VCs, other times with mDLs, but usually in proprietary ways. Some are bound with biometrics, others with passkeys. Some are focused on solving a problem in a specific industry, others in a specific geography.
5. Stuff happens
China to let banks pay interest on digital yuan to drive adoption
Via Jun Hiraga—Binance Weighs US Strategy as Billionaire Zhao Regains Clout
The S.E.C. Was Tough on Crypto. It Pulled Back After Trump Returned to Office.
Larry Fink and Rob Goldstein on how tokenisation could transform finance
Circle stablecoin for ‘banking-level privacy’ to launch on Aleo blockchain | Fortune
Via Mitja Simcic—Deblock secures €30M Series A to expand on-chain banking in Europe